California Personal Injury : How Insurance Companies Evaluate Premises Liability

California Personal Injury: How Insurance Companies Evaluate Premises Liability
When someone is injured because of a potentially unsafe property condition, an insurance claim may help cover medical expenses, lost income, and other losses. However, insurance companies do not automatically approve claims simply because an accident occurred. They review the available evidence, assess responsibility, and estimate the potential value of the claim. Understanding this process can help injured individuals make informed decisions about their premises liability cases in California.
How Insurers Assess Liability and Evidence
One of the first questions an insurance company considers is whether its policyholder may be legally responsible for the injury. In California, property owners and other parties responsible for a property may have a duty to use reasonable care to maintain safe conditions. Insurers examine whether a hazardous condition existed, whether the responsible party knew or reasonably should have known about it, and whether reasonable measures were taken to prevent or address the danger.
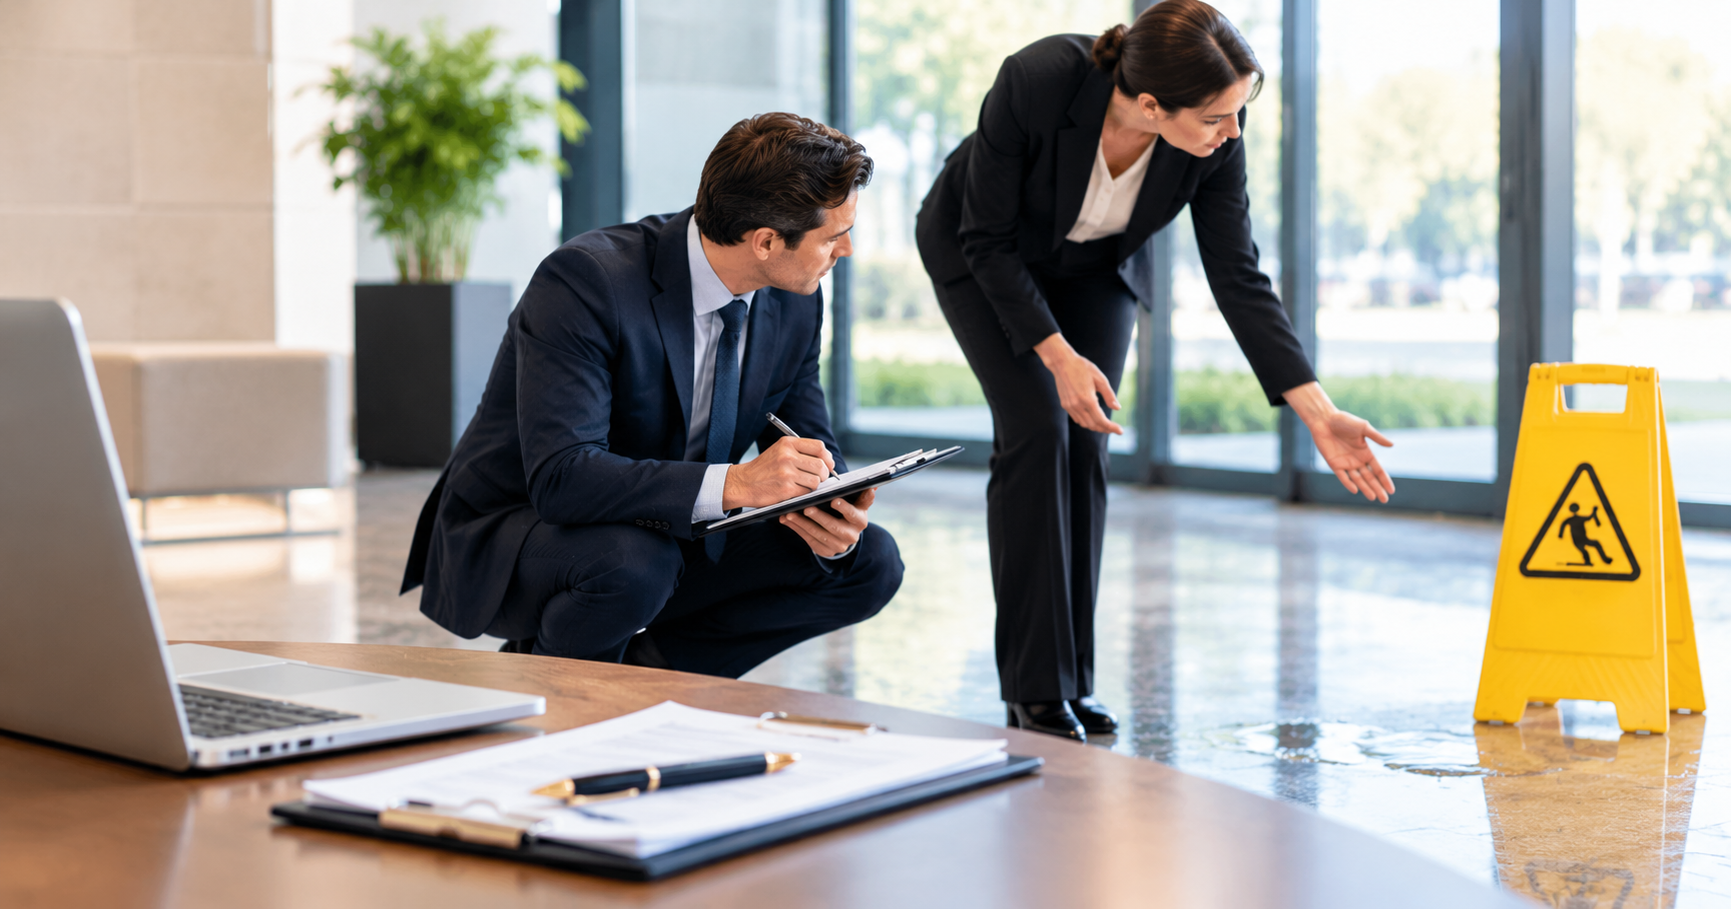
Evidence plays an important role in this assessment. Insurance adjusters may review photographs, incident reports, witness statements, maintenance records, inspection logs, and available surveillance footage. For example, in a slip-and-fall case, evidence that a spill remained on a store floor for an extended period may be relevant to whether the store had an opportunity to discover and address the hazard.
Insurers may also examine how the accident happened and whether other factors contributed to the injury. California follows a comparative fault system, meaning an injured person’s compensation may be reduced if that person is found partly responsible. The extent of any reduction depends on the circumstances and the allocation of fault.
How Insurers Evaluate Injuries and Claim Value
Insurance companies typically review medical records, treatment bills, doctors’ assessments, and other documentation to understand the nature and extent of an injury. They may consider whether the treatment is related to the accident, whether additional care is expected, and how the injury affects the person’s ability to work and carry out daily activities.
A claim may include economic losses, such as medical expenses and lost earnings, as well as non-economic losses, such as physical pain, emotional distress, and reduced enjoyment of life. The value of these losses depends on the evidence and the specific circumstances. Insurers may question certain expenses, dispute the severity of an injury, or argue that a pre-existing condition contributed to the person’s symptoms.
An insurance company’s initial settlement offer may not reflect the full extent of a person’s losses, particularly when treatment is ongoing or future effects remain uncertain. Reviewing the supporting evidence and understanding the potential consequences of accepting a settlement can be important before making a decision.
Conclusion
Insurance companies evaluate premises liability claims by examining responsibility, available evidence, the extent of the injuries, and the financial and personal impact of the accident. Keeping relevant records and understanding the claims process may help injured individuals protect their interests.
This article provides general information about California premises liability claims and is not legal advice. Every case is different, and insurance policy terms and legal deadlines may affect available options. Consider consulting a qualified California personal injury attorney to discuss your individual circumstances and understand your legal rights.