California Personal Injury : Understanding the Claims Process for Property Damage Claims

California Personal Injury: Understanding the Claims Process for Property Damage Claims
Introduction
Property damage after an accident can lead to unexpected repair costs, replacement expenses, and disagreements about who should pay. In California, the claims process generally involves documenting the damage, notifying the appropriate insurance company, establishing responsibility, and determining the value of the loss. Understanding the steps involved can help claimants prepare their documentation and make informed decisions throughout the process.
Filing a Property Damage Claim and Providing Evidence
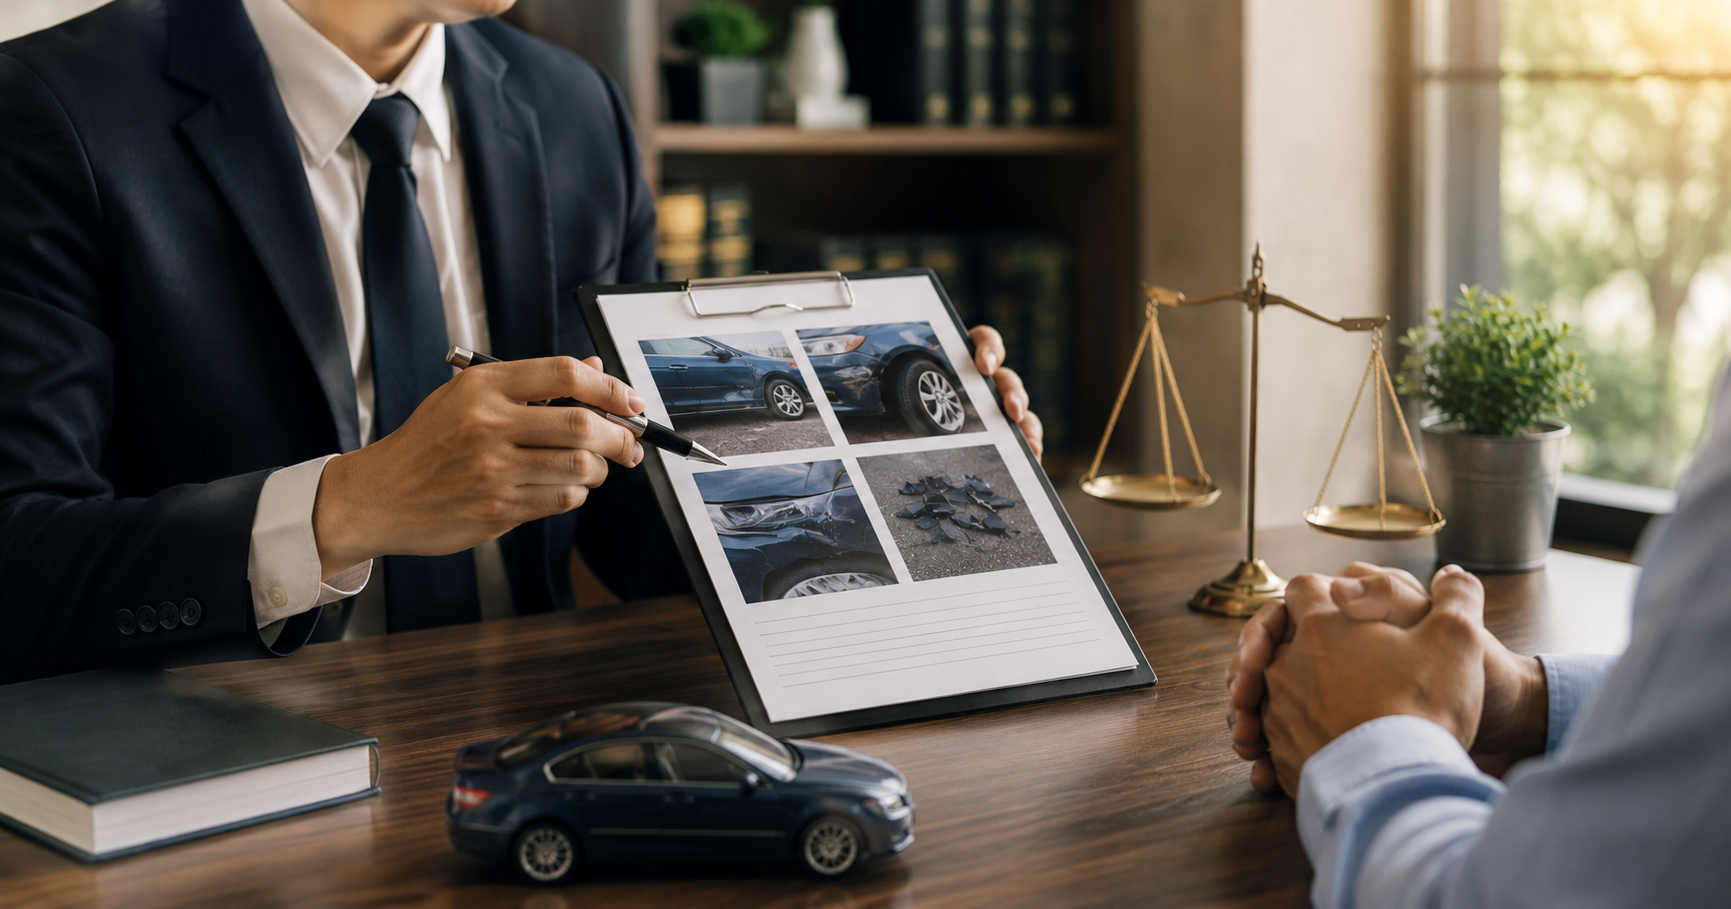
The process usually begins by notifying the responsible party’s insurance company or contacting your own insurer, depending on the circumstances and available coverage. After an incident such as a vehicle collision, it is important to record the damage, gather relevant information, and keep copies of any reports or correspondence. Photographs, witness details, repair estimates, receipts, and proof of ownership may help support the claim.
Once the claim is reported, the insurer may assign an adjuster to review the circumstances and assess the damage. The adjuster may request additional information, inspect the property, or arrange for a professional evaluation. Promptly responding to reasonable requests can help move the investigation forward. However, claimants should review documents carefully and keep records of statements and communications made during the process.
The insurer will also consider whether its policy covers the loss and whether its insured party was responsible. If responsibility is disputed or more than one party contributed to the incident, resolving the claim may take longer. California’s comparative fault rules may affect how responsibility and compensation are determined in applicable cases.
Evaluating the Settlement and Resolving Disputes
After reviewing the evidence, the insurance company may make a settlement offer. The amount can depend on repair costs, the property’s value before the incident, applicable policy limits, and the terms of the insurance coverage. For example, a vehicle declared a total loss may be valued differently from one that can reasonably be repaired. The insurer’s assessment may not always match the claimant’s expectations.
If the offer appears insufficient, claimants can request an explanation of the valuation and provide additional supporting documents, such as an independent repair estimate or evidence of comparable property values. Depending on the circumstances, they may also ask for a further review, use applicable dispute-resolution procedures, or explore other legal options.
It is important to understand what a settlement agreement covers before accepting it. Some agreements may resolve the property damage claim without resolving separate claims for physical injuries. Deadlines may also apply to legal claims, and certain claims involving government entities have special procedures. Seeking legal guidance early can help clarify available options and applicable time limits.
Conclusion
Understanding the property damage claims process can help you organize evidence, evaluate an insurance offer, and respond to disputes more effectively. If liability is contested, compensation appears inadequate, or the claim becomes complicated, consider consulting a California attorney.
This article is provided for general informational purposes only and does not constitute legal advice. The outcome of a property damage claim depends on its specific facts, applicable law, and insurance policy terms. Consult a qualified attorney for advice regarding your individual circumstances.